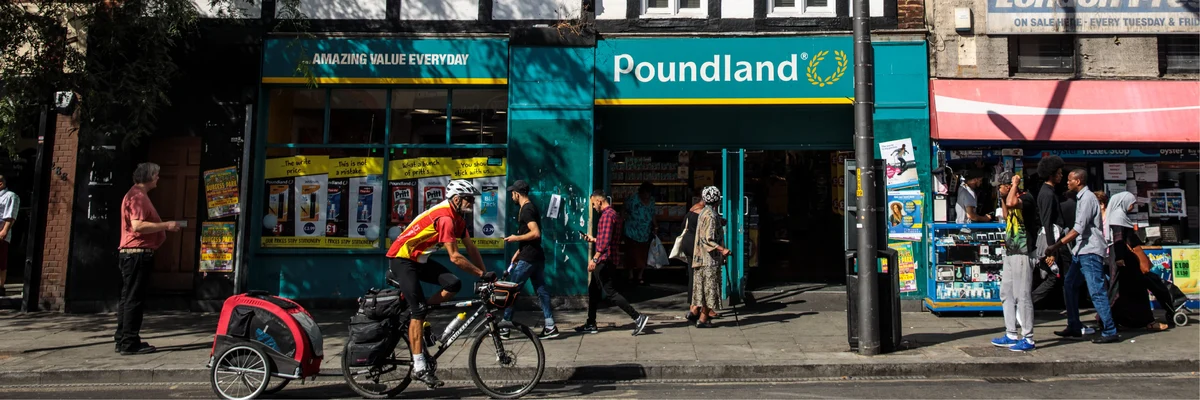
Poundland’s owners are reportedly mulling a “rushed sale” of the company in a bid to avoid administration. Could a change of ownership turn the tide for the struggling budget brand? New analysis from YouGov BrandIndex highlights some of the challenges facing Poundland.
One, for example, is that over the past five years (1 October 2021 – 1 October 2026), its Consideration score has fallen notably. Our data shows Poundland’s scores were at 29.0 five years ago; as of our most recent data, they sit at 24.3 (-4.7). Over the same period, two key rivals have improved. B&M Bargains has seen Consideration rise from 36.7 to 39.9 (+3.2), while Home Bargains has registered an uptick from 35.1 to 39.2 (+4.1).
Value scores follow similar arcs for all three brands – with Poundland’s measure falling from by 3.0 points as B&M’s rising by 1.6 points and Home Bargain’s increasing by 3.2 points.
So, while its rivals have seen half a decade of positive movement, perceptions of Poundland have gone backwards.
BrandIndex/Profiles shows that over half of Poundland customers (54%) currently shop at Home Bargains, with a similar proportion shopping at B&M (56%). A majority would also consider these rivals (64% for Home Bargains and 64% for B&M).
One reason for this picture of weakness for Poundland and strength for its rivals may be that the brand is not outperforming its rivals when it comes to bang for buck – even among its own shoppers. Some 56% of Poundland’s current customers say the chain represents good value – which puts it roughly equal to both B&M (55%) and Home Bargains (57%). Meanwhile, 20% of the brand’s customers believe it represents good quality – similar to how they see B&M (21%), but below Home Bargains among Poundland’s own shoppers (27%).
Our data emphasises a pressing question for Poundland’s would-be buyer: How can the brand prove its value to the public – and its own customers – against competition that appears to be getting stronger?
Methodology
YouGov BrandIndex collects data on thousands of brands every day. Scores are reported as net scores from –100 to +100 or percentages based on daily surveys of UK adults. Data is weighted by age, gender, region, social grade, and ethnicity using a raking methodology.